
Dental care
Write routine cleaning, accidental dental injury and dental illness on separate lines. Ask which selected benefit handles each, instead of checking a single “dental included” box.
A broad name can describe very different contracts. Identify the plan first, then check which part pays for each kind of care.
If you saw the phrase on a Nationwide document, look for the exact plan name, insurer, state form, policy dates and any endorsements. Nationwide still hosts a legacy California Whole Pet with Wellness sample that combines medical and preventive expenses. That archived sample establishes what that particular contract described; it does not establish that the same product is open to new applicants where you live.
If you are shopping generally, translate “whole pet” into a care list instead of searching for a promise of completeness. You might want protection for an unexpected illness, routine examinations, vaccines, dental cleaning and a planned procedure. Each item needs a place in the offered documents.
For an existing policyholder, the current renewal certificate and amendments matter more than an old brochure. Ask the insurer whether the offer in front of you continues the same contract or replaces it. This guide does not claim that every Nationwide customer has the same plan or has received the same renewal change.
| Layer | What to locate | Where “whole” can mislead |
|---|---|---|
| Medical insurance | Accident and illness definitions, exclusions, cost sharing and payout limits. | A broad list of diagnoses does not remove pre-existing-condition or other contract restrictions. |
| Routine-care benefits | Named services, allowances, frequency and benefit period. | An included service may have only a limited contribution toward its bill. |
| Non-insurance services | The agreement for a clinic plan, discount or advice service. | Access to a service is not necessarily reimbursement for veterinary treatment. |
Use the layers as headings on your own comparison sheet, then enter each promised benefit only once. Ask which organization owes the benefit and whether it is delivered as a service, discount or insurance payment. That keeps an advice feature from being counted as medical coverage and a clinic visit package from being counted as an emergency fund.
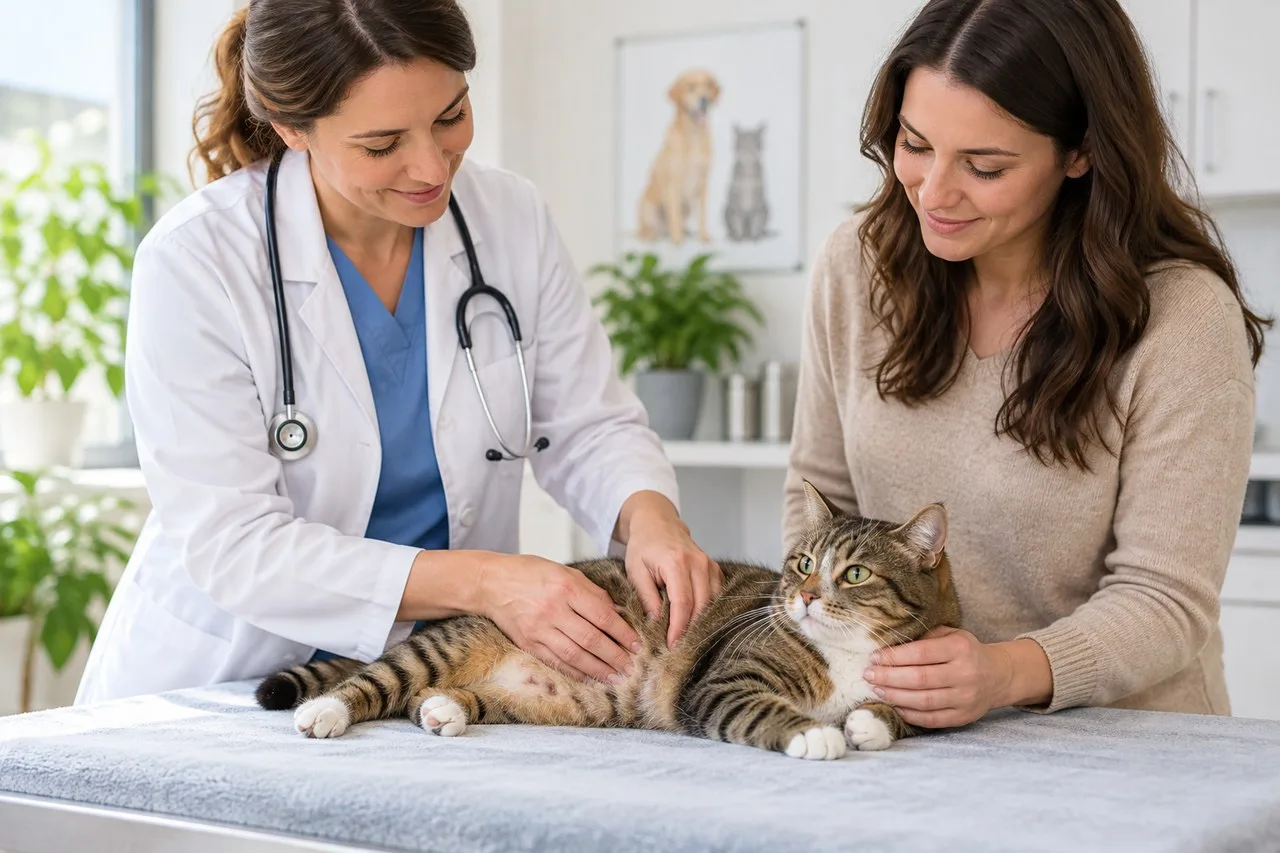
Imagine a cat comes for a planned checkup and the veterinarian also investigates a new symptom mentioned during the visit. The clinical team should record what actually happened. For insurance purposes, ask how the examination, routine services and symptom-related diagnostics are classified under the selected benefits.
Do not assume everything belongs to wellness because the appointment began as a checkup. Equally, do not assume an illness claim absorbs every vaccine or routine screening item on the invoice. Obtain an itemized bill, then ask the administrator which benefit and limit applies to each disputed charge.
This is an allocation question, not permission to relabel a service. If the paperwork is inaccurate, request a factual correction from the practice. If the description is accurate but the insurer applies a different benefit, ask for the relevant policy section and a written explanation. A bundled plan is most useful when you can follow that reasoning.
Write routine cleaning, accidental dental injury and dental illness on separate lines. Ask which selected benefit handles each, instead of checking a single “dental included” box.
Look for the actual spay, neuter or other preventive procedure in the benefit schedule. Check eligibility and any shared allowance before treating its full clinic price as reimbursable.
For a medical condition already under treatment, ask how it is handled now and at renewal. Optional wellness benefits do not answer that question.
Keep a separate budget for items without an applicable benefit. A convenient monthly payment does not turn an omitted service into a covered one.
Its Routine Vet Care Plus description does not include routine dental cleaning, even though other preventive or dental options may address it. Do not transfer an item from a different package into your quote.
Before choosing, save the medical policy, declarations, endorsements, wellness schedule and total payment commitment as one set. Mark the services you wanted but did not find. Then ask whether adding them changes the premium, uses a separate limit or requires another contract.
A bundle can still be convenient even when it leaves gaps. The useful conclusion is specific: which future medical risks are insured, which routine services receive a limited benefit and which costs remain yours. That is a stronger basis for choosing than the word “whole.”
These public references support the consumer or veterinary context. Named insurer details were checked in official product materials; the policy offered for your pet and state determines the actual terms.
Check current options for your pet and location, then compare the policy details, exclusions, costs, and eligibility before choosing.